For years, a proxy advisor recommendation worked as a forecast. Read the ISS report, read the Glass Lewis report, and you had a reasonable estimate of where the vote would land. Companies built their activism preparedness around that forecast. Satisfy the benchmark policy, secure the recommendation, and the vote would follow.
That forecast is losing accuracy. Benchmark voting policies are being unbundled into customized frameworks. Regulatory and legal pressure has reduced the weight a single recommendation carries. The largest institutions are splitting stewardship functions and voting with their own frameworks, and retail voting programs are putting more shares in the hands of people who never read a proxy advisor report at all.
The consequence is simple to state and hard to prepare for. Every meaningful holder is becoming their own proxy advisor. The company’s argument no longer gets summarized by an intermediary. It gets read, watched, and judged directly.
Activism preparedness is the state of having the narrative, materials, and production capability in place to make that case before an activist makes contact. It is not a monitoring posture or a relationship map, though both help. It is a question of whether the argument already exists in a form that survives a hostile read.
Three shifts define the current environment, and they compound each other.
First, proxy advisor influence is fragmenting. Analysis published on the Harvard Law School Forum on Corporate Governance describes a 2026 proxy season in which the predictable centers of gravity, benchmark policies and cohesive passive-investor stewardship, are loosening at the same time. Proxy advisors still matter. Their recommendations just no longer function as a shortcut for the outcome.
Second, private engagement has replaced the public campaign as the default form of pressure. The letter, the meeting request, the pointed question at a conference: these arrive before any 13D filing, and often instead of one.
Third, settlement is the default outcome. Law firm data republished on the Harvard Forum in June 2026 reported that activists had obtained 24 of the year’s 25 board seats through settlement rather than a contested vote. Settlements resolve in weeks. That compresses the window in which a company has to make its case to almost nothing.
Layered over all of this, the universal proxy card means shareholders evaluate directors one at a time. Activists respond by assembling stronger slates and targeting the most vulnerable individual directors, rather than trying to win the whole board.

It is tempting to treat this as a data problem. Better shareholder identification, a more current relationship map, closer tracking of engagement requests. Those are useful, and any competent IR function should have them.
But the deeper change is about who evaluates the argument and in what form.
When a proxy advisor summarized your case, the materials only had to satisfy a checklist. The proxy statement was written for a reader who had a policy, applied it, and produced a recommendation that thousands of votes followed. Design, clarity, sequencing, and persuasion mattered at the margin.
Now the materials are the argument. A stewardship team at a large index fund reads the proxy statement and the fight site and decides. A retail holder reads whatever is easiest to understand. An analyst at an active manager watches the CEO’s video and forms a view about credibility in ninety seconds. None of them are waiting for a recommendation to tell them what to think.
That means the quality of the argument, and the quality of the way it is built and delivered, now carries the vote.
Most companies that describe themselves as prepared can spot an activist. Few can respond to one.

The capital allocation story exists, but it lives inside an earnings script and a ninety-slide board deck. Neither was designed for someone looking for a weakness to read. The board’s case for itself is a set of two-paragraph biographies in a proxy statement. Most companies scope the proxy fight site the week after the 13D lands, so people who have never seen the narrative before build the first version under a deadline. The team shoots the CEO’s video statement in a conference room in an afternoon, and it looks like it.
None of these are failures of judgment. They are failures of sequencing. The company waited to build the argument until there was an audience for it, and by then the settlement clock was already running.
In this environment, preparedness means maintaining a small set of assets before the company needs them and keeping those assets approved and current.
Capital allocation critique remains one of the most common activist entry points. The defense is not a talking point. It is a designed, versioned narrative that explains the logic behind buybacks, dividends, reinvestment, and M&A in a form a skeptical reader can follow. Build it as a presentation, keep it current each quarter, and make sure the CFO can deliver it without a script. Where it belongs is the same place your presentation design discipline already lives, alongside the Investor Day deck, not in a separate emergency folder.
If shareholders vote director by director, each director needs a case. That means more than a biography. It means a short, designed module for each board member: why they are on the board, what they have contributed, and how their experience maps to the company’s strategy. Build these as presentation components and as short video pieces. Store them. Refresh them annually. When a slate arrives, the board has already made its argument.
A proxy fight website should exist before the fight. Build the architecture, the design system, the messaging framework, and the approval workflow in a quiet quarter. Populate it with the standing narrative and the director modules. Leave it dark. The team responsible for proxy fight sites and micro-sites should treat this as standing infrastructure, the way a company treats its IR site, not as a rush project. When a contest becomes public, the company launches a site built around an argument that counsel has reviewed and management has rehearsed, rather than one the team assembled over a weekend.

In a contest, the CEO’s face carries the credibility argument. That requires the company to rehearse its on-camera capability and work with a corporate video production partner who already knows the narrative, the lighting, the location, and the approval chain before the first shoot.Companies that have a standing relationship of this kind produce an executive statement in days. Companies that do not spend the first week of a contest finding a crew.

Since private engagement has replaced the public campaign, the most important document in activism preparedness may be the one nobody outside the room ever sees. When a large holder asks for a meeting with the CFO, what does the company bring? The answer should be a compact, designed deck that presents the strategy, the capital allocation logic, and the board’s composition as a coherent argument. The audience is one stewardship team. The stakes are the same as a public campaign. Build it with the same discipline.
Two audiences are growing in influence, yet companies almost never design for them.
Retail holders, through voting programs and pass-through voting, now hold a meaningful share of the votes that used to sit in concentrated institutional blocs. They do not read benchmark policies. They read whatever is clear, short, and visual. A proxy site built for a governance specialist will lose them.
The second audience is software. A Harvard Forum analysis in April 2026 examined what large language models recommend when asked to act as proxy advisors in contested elections. The most frequently cited reason for picking a side was the ISS or Glass Lewis recommendation. As those recommendations fragment into customized frameworks, AI tools fall back on the primary materials: the proxy statement, the fight site, the press releases. Structure, headings, plain-language answers, and consistency across documents become inputs to how a machine summarizes the company’s case for a human who then votes.
This is the same discipline that makes an Investor Day microsite work for a search engine. It now applies to a proxy contest.
The instinct in an activist situation is to treat communications as a separate workstream, staffed after the legal and financial advisors are in place. That sequencing made sense when a proxy advisor recommendation carried the vote. It does not make sense when the materials are the argument.
An activist campaign is an unscheduled Investor Day with a hostile co-host. The company has to present its strategy, its capital allocation logic, its board, and its leadership to an audience that will decide the outcome, in a compressed window, across a site, a set of presentations, and video. Every one of those is a production problem. The narrative is infrastructure for understanding. Design is what makes it readable under pressure. Video is what makes credibility visible. The site is where all of it has to hold together.
Companies that already run Investor Day production with that discipline have most of the infrastructure an activism response requires. The gap is sequencing. Companies have to build the assets before the audience arrives.
A company can assess its own activism preparedness with five questions:
A “no” on any of these is not a crisis. It is a scope. And it is far easier to close in a quiet quarter than a contested one.
If your capital allocation story only exists inside an earnings script, it is not ready for a hostile read. That is a solvable problem. The companies that solve it before they need to are the ones that get to negotiate from a position of clarity instead of catching up.
Activism preparedness is the state of having the narrative, materials, and production in place to make a company’s case directly to shareholders before an activist makes contact. It goes beyond monitoring and relationship mapping. It means a current capital allocation narrative, director-level story modules, a dormant proxy contest site, executive video capability, and a private engagement deck that already exist and are approved.
Institutions are replacing benchmark voting policies with customized frameworks, regulatory and legal challenges have reduced the influence of a single recommendation, large investors are voting under their own stewardship frameworks, and retail voting programs are shifting more votes to holders who do not follow proxy advisors.The result is that a recommendation no longer functions as a reliable forecast of the outcome.
The universal proxy card lets shareholders vote for individual directors across both slates rather than choosing one full slate. That means investors evaluate each director on their own merits.Companies need a designed, ready argument for every board member, not just a set of biographies in the proxy statement.
A proxy fight website should present the company’s strategy, capital allocation logic, board composition and individual director cases, a clear response to the activist’s claims, executive video, and all relevant filings, in a structure that works for institutional readers, retail holders, and AI tools. It should be built and approved before a contest becomes public and activated when needed.
Increasingly, yes. Analysis published on the Harvard Law School Forum on Corporate Governance in 2026 found that large language models asked to act as proxy advisors relied heavily on ISS and Glass Lewis recommendations. As those recommendations fragment, AI tools read primary company materials directly, which makes the structure and clarity of proxy documents and contest sites a factor in how votes are formed.

I have sat in two chairs during my career, and they face each other.
For years I sat on the client side of investor relations for the largest hospitality asset management firm publicly traded at that time. I lived the quarters, the investor days, the announcements that could not slip, and the moments when shareholder activism turned a normal week into a war room. Then I crossed the table. I co-founded an investor relations creative production agency built specifically for those moments. Earlier this year I presented this dual perspective to one of the leading strategic communications firms in the country, and the conversation that followed convinced me it was worth writing down.
This piece is for agency leaders. Not because agencies are the problem. Because agencies are closest to the fix.
Every public company has a short list of moments where trust is gained or lost based on execution. Investor Days. IPO roadshows. Management transitions. Activist situations. Transaction announcements. The strategy behind these moments can be months in the making. The judgment of them happens in hours.
Here is what I did not fully appreciate until I had worked both sides. The client and the agency are experiencing the same moment through different fears.
The client is worried about their audience. Investors, analysts, employees, the board. Trust with those audiences is gained or lost in real time, and there is no replay.
The agency is worried about the client. Their trust is gained or lost based on how the moment executes. A brilliant strategy that stumbles on stage does not get graded as a brilliant strategy.
Both sides face the same unforgiving math: high complexity, hard deadlines, no second chances. Which means both sides need the same thing. Strategic intelligence, creative excellence, and flawless execution, together, from the start. Not one or two of the three. All three.
In all my years on both sides of the table, I can count on one hand the failures I attribute to a bad strategy. Almost none of the breakdowns I witnessed came from weak thinking. The strategists were smart. The teams were competent. Everyone was well-intentioned.
The breakdowns came from fragmentation.
Too many vendors. Too many handoffs. A video team that never spoke to the presentation designer. A webcast provider who saw the run of show for the first time the night before. An event crew executing a stage design that contradicted the narrative the strategy team had spent months refining. Each vendor doing their fragment competently, and nobody accountable for the whole.
Investor relations and communications teams are still piecing together vendors and tools, each handling a fragment of what should be one unified, controlled experience. When the stakes are low, the seams don’t show. When the stakes go up, the seams are the first thing to tear.
When I moved from the client chair to the agency chair, three things became obvious quickly.
Most agencies outsource the services their clients judge them on. Very few firms have the internal resources to be an all-in-one solution, so production gets subcontracted to third parties. That is a rational business decision. It is also a quiet transfer of risk. The agency’s reputation now rests on vendors the client never chose and the agency may barely know.
Most production vendors don’t understand the IR landscape. They can execute. They can light a stage and cut a film. But they don’t know why a disclosure review changes an edit, why the sequencing of a guidance slide matters, or why an activist situation changes the tone of everything. They execute. They don’t develop strategy. In high-stakes capital markets moments, that gap is where mistakes live.
The integration gap is the opportunity. What the market lacks is a partner with a foundational understanding of the IR space and the creative acumen to produce work that holds up on the biggest stage. Not a strategy firm that dabbles in production. Not a production shop that skims a press release. A partner fluent in both.
Integration is not a philosophy. It shows up in specific moments. Three patterns come up constantly.
Management changes, major announcements, shareholder activism. These are the moments when a narrative needs visual components fast: explainer and narrative films, launch videos, and microsites built to hold and control the story. Speed and message control matter equally, which is why full-service video production and web need to run as one workstream, not two.
Pre-IPO roadshows and Investor Days. There are no second chances at a first impression. These moments demand live, hybrid, or virtual event production, executive films, animation, presentation design, and end-to-end project oversight, all pulling in the same direction. This is Investor Day production as a discipline, not a checklist of deliverables.
Sometimes the client already has the pieces. What they lack is orchestration. The internal point of contact is overwhelmed, and the agency needs someone acting as executive producer: managing vendors, owning timelines, overseeing logistics, and reducing risk for the agency and the client at once. This is the least glamorous version of the work and often the most valuable.
Earlier than you think. The pattern I saw repeatedly on the client side, and see now from the agency side, is simple: earlier involvement leads to broader impact and less risk.
When production joins at the end, it inherits decisions it cannot fix. The venue is booked, the deck is locked, the timeline is fixed, and the production partner is reduced to damage control. When production joins at the start, staging informs the narrative, the film supports the presentation, the microsite extends the event, and the whole moment reads as one coherent experience.
And to be clear about what this is not. A production partner should never replace an agency’s strategy. The right model enables the agency team to perform at its best and protects the long-term trust the agency has built with its client. The strategy firm owns the thinking. The production partner makes the thinking undeniable in the room.
If you lead a strategic communications or IR advisory firm, here is the honest audit I would run.
Look at your last three high-stakes client moments. Count the vendors. Map the handoffs. Ask who was accountable for the whole experience rather than a fragment of it. If the answer is “our account lead, on top of everything else,” you have found your exposure.
Your clients do not separate your strategy from its execution. Investors in the room do not either. They evaluate confidence, coherence, and credibility as a single impression. The firms that win the next decade of this work will be the ones that close the gap between what they recommend and what actually happens on stage, on screen, and online.
I have sat in both chairs. The view is better when they are on the same side of the table.
Jeremy Robinson is the co-founder and CEO of Cardboard Spaceship, a production partner for investor relations and high-stakes corporate communications. If a moment that matters is on your calendar, the best conversation is the one that happens early. Reach out at [email protected].
What is an investor relations production partner? A production partner for IR is a firm that executes the visual and experiential components of investor communications, including video, live events, presentation design, and microsites, with working fluency in capital markets context. It complements a strategy or communications firm rather than replacing it.
Why do Investor Days break down even with strong strategy? Most breakdowns come from fragmentation rather than weak ideas. When multiple disconnected vendors each handle a piece of one investor experience, accountability gaps appear at exactly the moments when deadlines are least forgiving.
Should agencies outsource production for high-stakes client moments? Outsourcing itself is not the problem. Outsourcing to vendors who lack IR fluency, without a single point of accountability for the full experience, is. Agencies protect their client relationships by choosing integrated partners who understand the stakes.
When should a production partner join an engagement? As early as possible. Early involvement lets production decisions inform strategy, broadens the partner’s impact, and reduces execution risk. Late involvement limits the partner to damage control.
Every IR team plans for the expected: earnings, guidance, investor meetings, and board updates. Then an executive departure, market rumor, activist approach, or unexpected miss changes the agenda in hours.
Q4’s August 2026 recap of Confessions of an IRO: Episode 3 brings together Jamie Stanton, Irina Zhurba, Isabel Vilela, and Geoff Callow to examine those moments. Their discussion offers practical lessons for investor relations teams. It also exposes a production reality: teams can move only as fast as the communication system they built before pressure arrived.
Investor communication infrastructure combines a current equity narrative, trusted executive voices, established digital channels, practiced response workflows, and consistent content production. Companies maintain these assets before a crisis so they can verify facts, respond quickly, and protect credibility under pressure.
When unexpected news breaks, analysts call, investors ask questions, and leadership feels pressure to respond immediately. The IR team should first confirm what happened, determine any disclosure obligations, and align legal, finance, corporate communications, and leadership around the facts.
The Q4 panelists urged teams to distinguish among market rumors, reporting errors, executive departures, and material events before they speak. Geoff Callow cautioned against a reflexive response without complete information. A short acknowledgment can protect credibility while the team verifies the details.
Standing infrastructure gives teams the confidence to wait for accurate information. A prepared team already knows who approves the message, which channel will carry it, who will speak, and how production will support the response. That clarity prevents silence from turning into panic.
Activist pressure rarely starts with a public letter. In the Q4 discussion, Callow described an activist who engaged privately for 12 to 18 months before going public. Zhurba noted that a public campaign can continue for two to three years.
IR teams should monitor the share register, study changes in investor tone, and listen for the question behind each repeated concern. An activist gains leverage when existing shareholders stop trusting management’s explanation and start considering a competing story.
That long runway creates an opportunity. Teams can document investor concerns, update the equity narrative, and strengthen shareholder relationships before a campaign starts. Our guide to why activist defense starts before the first letter explains how companies can use that time.
Once a contest reaches the public, the company needs a sustained content operation rather than a single press release. Purpose-built microsites and proxy fight sites give shareholders one source for the company’s argument, evidence, materials, and answers.

Management may focus on the five-year opportunity while investors focus on the next few quarters. Strong IR teams hold both views at once and identify the evidence that separates them.
Zhurba recommended bringing investors’ exact words into leadership conversations. Verbatim perception feedback gives executives evidence instead of opinion. She also warned that one miss can erase a year of credible calls, so teams should set expectations they can meet.
When investors misunderstand the business, a capital markets day can reset the narrative. A dense deck and conference line cannot carry a complex repositioning. The market needs clear sequencing, strong presentation design, confident speakers, and disciplined Investor Day production.
Format performs strategic work. Investors judge the plan and the team’s command of it at the same time. Our guide, Your Investor Day Is a Broadcast. Treat It Like One., explains how production quality supports the investment narrative.
A CEO who first appears online during an activist campaign can look defensive. An executive who communicates consistently through video, interviews, articles, and social channels enters the same moment with an audience and a record of credibility.
Corporate communications and IR should define the subjects each executive can credibly own, create a regular publishing cadence, and let formal disclosure lead every market-sensitive message. Practice also matters. Executives who rehearse on camera communicate with greater clarity when the stakes rise.
A full-service video production program helps leadership maintain that presence. No team can create trust in a week. Teams must earn and reinforce it over time.
Cardboard Spaceship helps corporate communications teams turn executive expertise into consistent, credible video content.
Prepared companies maintain five connected assets:
Prepared companies keep the narrative current, maintain a digital home for the story, rehearse leaders during calm periods, and treat major events as strategic resets. When a crisis changes the plan, those companies respond with the calm of a team that trusts its delivery system.
Preparation cannot prevent every surprise. It changes the quality and speed of the response. In capital markets, investors remember both.
Audit your communication infrastructure before you need it. Does leadership maintain an established voice? Do investors have a digital source of truth? Can your team publish a credible response within a day? If any answer gives you pause, start the work now.
If your calendar includes a high-stakes moment, or your team wants one less system to build under pressure, talk with Cardboard Spaceship.
The IR team should verify the facts, identify any disclosure obligations, and align legal, finance, corporate communications, and leadership before it responds. A short acknowledgment can give the team time to confirm the details without creating speculation.
Companies protect credibility when they communicate through established channels, match every claim with evidence, set expectations they can meet, and update investors consistently. Preparation gives teams the confidence to prioritize accuracy over speed.
An activist may engage privately for 12 to 18 months before going public, and a public campaign can continue for two to three years. Companies need a sustained communication program for the full period.
A capital markets day helps a company explain its strategy, operating model, leadership, and long-term value drivers in greater depth. Companies often use the event to address a valuation gap that stems from market misunderstanding.
Executives who communicate consistently build familiarity and trust before pressure arrives. During a crisis, those leaders can extend formal disclosure through channels that investors already recognize.
A microsite gives shareholders one controlled source for the company’s argument, evidence, presentations, video, and FAQs. That clarity helps companies maintain a consistent reference point during proxy contests and other high-stakes situations.
A public company uses a dedicated proxy fight website that it controls during a contested shareholder vote to explain the board’s case, show the evidence behind it, publish updates that counsel has approved, and tell shareholders how to vote. Unlike a standard investor relations site, the company designs it around one decision and one deadline.
That sounds straightforward until the contest starts moving.
An activist publishes a new letter, a reporter calls for comment, a proxy advisor asks a question that exposes a weak point in the narrative. Counsel revises language that has already made its way into a layout. Meanwhile, the shareholder arriving on the site may have ten minutes, little context, and two competing versions of the same company in front of them.
This is why the best proxy fight sites do not look like document libraries with campaign headlines. They make structured arguments. They help a reader understand what the board believes, why it believes it, what supports the claim, and what the reader should do next. Also, they give every team working on the contest one source that everyone has approved.
When other people are interpreting your story in public, that source matters.
A proxy contest rarely reaches shareholders as one clean, uninterrupted argument. It arrives in pieces: proxy statements, shareholder letters, activist presentations, earnings commentary, news coverage, proxy advisor reports, social posts, and conversations with investors. By the time someone forms an opinion, they may be reacting to a summary of a summary.
The company’s proxy contest website gives that fragmented conversation a center. It does not replace the proxy statement, SEC filings, direct shareholder outreach, or the work of the proxy solicitor. It gives those materials a clear public structure.
That structure should clearly answer four answer for shareholders:
Internally, a site also forces IR, communications, legal, the proxy solicitor, outside advisors, and the production team to work from the same narrative spine. In a contest, small inconsistencies can become large distractions. A well-run site gives the campaign a current source of truth.
Every contest is different, but the strongest sites tend to contain six working parts. The important word is working. Each part should help a shareholder evaluate the decision, not simply prove that the company has published a lot of material.
The site should open with what the board is for, not only what it opposes. That usually means a concise account of the company’s strategy, the progress already made, the work still underway, and the reason continuity or change is in shareholders’ best interests.
This is where many defense sites lose their balance. If the activist sets the agenda and the company spends the first screen rebutting it, the site feels reactive before the reader reaches the evidence. Lead with the company’s case. Put the dispute in that context.
The long version can live in the filings. The website needs the version a smart, skeptical person can follow between meetings.
In a contested vote, adjectives are liabilities. “Strong performance” invites an argument. A figure with a date, a comparison period that the team states clearly, and a visible source give the reader something to evaluate.
Present performance data, strategic milestones, capital allocation, governance changes, and the history of shareholder engagement as exhibits rather than decoration. Place source notes near each claim. Make dates and definitions easy to find. If a chart uses a selected peer group or time period, say so plainly.
The practical rule is simple: if a claim matters enough to influence the vote, make its support easy to inspect
Standard corporate bios answer, “Who is this person?” A proxy fight site has to answer a harder question: “Why is this director right for the company now?”
That may require drawing out experience relevant to the strategy under debate, the board’s refreshment and succession work, committee leadership, operating expertise, or direct accountability for the next phase of the business. The goal is not to inflate a résumé. It is to connect qualifications to the choice on the ballot.
Short director videos can help when they add something a bio cannot: judgment, command of the issues, and a sense that the people asking for the vote are willing to address shareholders directly. A three-minute answer with a point will usually do more work than a ten-minute statement that a committee has polished into submission.
The initial launch is only the first version of the site. New letters, presentations, recommendations, press releases, and responses may need to appear as the campaign develops. A useful proxy defense site anticipates that from the beginning.
That means a news and resources area with dates, descriptive titles, and a clear distinction between the company’s argument and the underlying materials. It also means reusable page modules that can absorb a new rebuttal or evidence point without turning the homepage into a running transcript of the fight.
The tone matters here. A strong rebuttal stays specific, cites its sources, and matches the scale of the claim. Not every accusation deserves the largest headline on the page.
The site should tell shareholders exactly what action to take, how to take it, and when to act. Legal counsel and the proxy solicitor should control the exact language and mechanics.
Clarity is particularly important under the SEC’s universal proxy rules, which generally require proxy cards in non-exempt contested director elections to list nominees from both sides. The rules give shareholders more flexibility, but a ballot with every nominee also makes precise, situation-specific instructions essential. The website should reinforce the instructions that counsel and the proxy solicitor approved, not paraphrase them creatively.
A proxy fight website is not a normal campaign page. Treat it as part of a regulated shareholder communication from the first working session. Counsel should decide which language to review, which materials the company must file or disclose, and when the team can publish them.
That changes the production process. Teams cannot leave sources and footnotes until the end. They need version control once counsel approves the copy. Design must accommodate legal language without burying it. The publishing team must track every change and record which version counsel cleared.
Compliance is not the final gate after the creative work. It is one of the conditions the creative work has to solve.
The obvious answer is shareholders. The more useful answer is that several audiences use the same site in very different ways.
Institutional governance teams and proxy advisory analysts tend to follow claims back to their sources. They care whether numbers reconcile, whether the board’s case addresses the actual criticism, and whether the evidence is current.
Retail shareholders need more orientation. Many will not have followed every filing or understand why two parties are asking for their vote. Plain-language context and visible voting instructions are not a simplification of the case. They are part of making the case usable.
Reporters and market commentators work at speed. When the company makes its position difficult to summarize, others often summarize it poorly. Clear headings, dated facts, and concise statements make the site a more reliable reference.
Then there is the discovery layer between the site and all three groups: search engines, news aggregators, and AI assistants. These systems are not voters, but they increasingly shape the first explanation someone sees. The answer is not to write robotic copy for a machine. Write important facts so they stay accurate when search tools and AI assistants extract them: state the conclusion early, keep its evidence close, use descriptive headings, and avoid leaving essential context three paragraphs away.
The rule is the same whether a person reads the full page or first encounters a summary: the point should survive the excerpt.
The exact group varies, but a live proxy contest site often brings together investor relations, corporate communications, internal and outside counsel, the proxy solicitor, financial communications advisors, executives, and the board. The web and production team works inside that group rather than beside it.
The kickoff call presents the easy part. The team still has to design an approval path that can move when the contest does.
One team may own the narrative. Another validates financial claims. Counsel reviews language and determines filing treatment. The proxy solicitor shapes voting instructions and shareholder support details. Directors and executives have limited windows for interviews. Developers may hold an update that counsel has approved while another team continues to revise a related paragraph.
That work cannot wait for a tidy weekly handoff. Teams need parallel tracks, clear decision-makers, strong version control, and a fast route from material change to publication. Ask any prospective production partner how it would handle a substantive activist letter on Tuesday and publish a response by Thursday. The answer will tell you more than a portfolio reel.
After counsel approves the material, a focused launch can move to a live site in days. A fuller build may take two weeks or longer, depending on the content, video, technical requirements, and review process. Development rarely creates the bottleneck. The readiness of the narrative, the evidence, the directors, and the people who must approve all three usually sets the timeline.
This is why “How fast can you build it?” is not quite the right question. A better one is, “How much of the case is already ready to use?”
If the team still needs to settle the narrative, source performance claims, schedule board members, and approve voting language, a fast web team cannot recover all of that time at the end. It can only compress the risk.
The site itself may remain dormant, but much of the work should happen before an activist campaign becomes public.
In practical terms, preparedness means having four things in usable condition:
Companies do not waste that work if a contest never arrives. The same narrative and evidence support investor days, earnings communications, governance engagement, leadership changes, and other moments when the company needs to explain itself under scrutiny.
Preparedness does not mean publishing a defense against an attack that has not happened. It means avoiding the more expensive mistake of deciding what the company stands for after someone else has defined it.
Credibility usually comes from restraint.
The site should feel like the company at its most composed, not like a special-situations template wearing the company’s logo. Brand matters because it signals continuity and confidence, but the design cannot compete with the evidence. Motion should guide attention, not manufacture urgency. Video should let accountable people speak, not turn directors into campaign talent.
Most of all, a skeptical reader should be able to test the argument by moving from a claim to the supporting number, source, filing, or timeline without losing the thread.
That was the central production challenge in Cardboard Spaceship’s proxy defense site for Victoria’s Secret & Co.. VS&Co had already documented a substantial public record across filings, earnings materials, letters, and releases. Working alongside Edelman Smithfield and the broader advisory group, the team brought the strategy, performance case, board qualifications, voting information, source materials, and director videos into one coherent experience. Content, design, development, video, and review moved in parallel because the calendar required it.
Shareholders ultimately re-elected every board nominee. That outcome belonged to the company, its board, its advisors, and its shareholders. The site made a narrower but still important contribution: when someone went looking for the board’s case, the site kept that case organized and ready for scrutiny.
These sites may use some of the same content, but they do different jobs.
The corporate IR site is the permanent record. It serves many audiences over time and houses filings, results, governance information, events, and company news.
An Investor Day microsite centers on an event. It gives the strategy a stage, organizes the agenda and speakers, and carries presentations, webcast access, and replay content.
A proxy fight website centers on a decision. It makes an argument, answers a competing argument, maintains a live record of campaign materials, and directs a shareholder toward a vote.
The strongest companies keep all three consistent. The numbers should reconcile. The strategy should sound like the same strategy. The experience changes because the audience’s task changes.
No. A dedicated proxy fight site is a strategic communications asset, not a standard filing requirement. However, companies may need to file or disclose content that solicits votes under SEC rules. Counsel should determine the requirements for the specific contest.
Companies and their advisors use several names for it: proxy contest website, proxy defense site, activist defense website, shareholder communications site, campaign site, or contested-situation microsite.
Yes. A company can give it a distinct section within the corporate or IR site, or launch it as a standalone site on its own domain. The right setup depends on the company’s infrastructure, security, approval process, desired speed, and plans to archive or retire the site after the vote.
Whenever a material development changes what shareholders need to understand or access and the advisory team approves an update. The team should name a site owner and establish a publishing process so new letters, filings, recommendations, responses, or voting information can go live quickly without creating conflicting versions.
Many companies retire or archive the campaign site after the meeting. The useful parts should return to the ongoing IR program: the narrative structure, evidence with clear sources, director content, and a publishing process that can handle scrutiny.
No. It supports the broader solicitation and communications effort. Direct engagement, SEC filings, advisor outreach, and voting support still do their respective jobs. The site gives those efforts a clear, accessible public home.
Facing a contested vote, or getting the underlying case in order while the register is quiet? Explore our proxy fight site and microsite capabilities or see how the Victoria’s Secret & Co. proxy defense site came together.
When SpaceX went public earlier this year, Elon Musk retained more than 82% of the voting power. On paper, that settles every argument before it starts. No proxy contest can touch the board. No activist can win a vote. The textbook levers of shareholder accountability simply do not apply.
So why are controlled companies now among the most active targets for shareholder campaigns?
A recent analysis from FTI Consulting, published on the Harvard Law School Forum on Corporate Governance, works through five fallacies that controlled companies tell themselves. The pattrn behind all five is the same. Voting control settles the ballot. It does not settle the story. And in modern capital markets, the story is where the fight actually happens.
We would push the argument one step further. Knowing you need to communicate is not the same as being built to do it. The controlled companies that protect their valuations treat investor communication as a system, with the same discipline they apply to operations.
The FTI authors make a point that every founder-led and family-controlled company should sit with. Activists targeting controlled companies are not trying to win votes. They are trying to win the narrative.
The recent campaigns at Snap and Zoom illustrate it. In both cases, activists had almost no path to victory at any shareholder meeting. They published anyway. Letters, presentations, public arguments about strategy and capital. The pressure worked the way public pressure always works, through reputation, media coverage, and the psychology of executives who do not enjoy being called out for underperformance.
For a controlled company, this changes the threat model completely. Your defense is not your share structure. Your defense is whether the market already understands and believes your story before someone else offers a competing version of it.
Controlled companies often assume the numbers will speak for themselves. The market disagrees.
Dual-class companies frequently trade at a discount to what an identical single-class business would command. Some investors are barred from the stock by mandate. Others simply price in the governance risk of decisions made without shareholder input. Research cited in the FTI piece, drawing on MSCI data, notes that controlled companies have underperformed widely held peers on both five-year and ten-year total shareholder return.
That discount is not fixed. It varies company by company, and it responds to communication. Investors penalize opacity and reward companies that explain their capital decisions in terms of value creation for all shareholders. Meta’s very public pivot away from metaverse spending, made under investor pressure despite founder control, shows that even the most insulated companies answer to sentiment when the cost of capital is on the line.
The lesson is uncomfortable but useful. Valuation is partly a communications outcome. Companies that treat it that way have an advantage over companies that treat it as a math problem.
The most common failure is treating investor communication as compliance. The 10-K gets filed. The earnings call gets scripted. The proxy statement goes out. Everything required happens, and nothing persuasive does.
Compliance-grade communication has three predictable weaknesses:
The companies that get this right run investor communication as an operating system, not a filing calendar. In practice, that looks like a sequence.
Commission the blinded study. Learn where the market’s version of your story diverges from yours. This is the raw material for everything that follows.
Not a refresh of last year’s deck. A genuine narrative architecture that answers the questions investors are actually asking, especially about capital allocation and the logic of the control structure itself.
Major strategic shifts should never debut in a press release. They should be seeded at conferences, developed on earnings calls, and given a full airing at an Investor Day where management can walk the market through the reasoning. Predictability is not boring. Predictability is what the market pays for.
A well-built IR microsite turns the narrative into infrastructure. When a challenge comes, whether from an activist, a skeptical analyst, or a surprised press cycle, the company’s complete argument is already published, organized, and easy to cite.
Here is what two decades of high-stakes investor communication has taught us. Investors do not just evaluate numbers. They evaluate confidence, coherence, and credibility. Production quality either reinforces those signals or quietly undermines them.
For controlled companies, this matters more, not less. The market is already discounting you for governance. A muddled presentation, a poorly staged Investor Day, or a CEO video that reads as defensive confirms the market’s worst assumption, that decisions inside the company are as unclear as the communication coming out of it.
The inverse is also true. A disciplined Investor Day, built on clean presentation design and supported by full-service video production, tells investors something no filing can. It says this management team can organize complexity, sequence an argument, and stand behind it in public. For companies bracing for a contested moment, investor microsites and proxy fight sites extend that same discipline into a permanent, controllable channel.
A strong narrative is not decoration. It is infrastructure for understanding. Controlled companies that build that infrastructure early rarely have to build it under fire.
If you lead communications at a controlled company, the question is not whether you can lose a vote. You cannot. The question is whether the market would recognize your story if someone else told a different one tomorrow.
Run the perception study. Close the gaps it reveals. Stage your strategy in public before your strategy surprises anyone. And treat the production of your investor communication, the events, the video, the presentations, the digital home, as seriously as you treat the strategy itself.
Control is a structure. Confidence is earned. If your next Investor Day, roadshow, or contested moment needs to earn it, that is the work we do.
Yes. Activists increasingly target controlled companies through public letters, presentations, and media pressure rather than proxy votes. The goal is to shape the narrative and force strategic debate, not to win a ballot.
A blinded perception study is a third-party survey of investors and analysts conducted without attribution, so respondents can speak candidly. It reveals how the market perceives the company, its strategy, and its story without the filtering that often happens in direct conversations.
Sequence it. Signal the evolution at conferences and on earnings calls before any announcement, then use a dedicated forum such as an Investor Day to walk investors through the full reasoning. Surprises get punished. Journeys get funded.
Arguably more than anyone. An Investor Day is the one moment a controlled company can address the governance discount directly, demonstrate management depth beyond the controlling shareholder, and present the complete equity story in a format built to persuade.
The second quarter of 2026 was the strongest stretch for new listings in years. One historic mega offering dominated the headlines, but the more useful signal sits underneath it. According to recent capital markets analysis, U.S. IPO volume rose meaningfully both quarter-over-quarter and year-over-year, Europe continued its recovery, and billion-dollar offerings appeared across technology, industrials, energy, and digital infrastructure.
The window is open. But it is not open for everyone in the same way.
The same analysis makes a point that should matter to every pre-IPO leadership team. Investors remained selective, favoring companies with differentiated growth stories and strong fundamentals. Read that carefully. Fundamentals alone did not carry the quarter. Differentiated stories did.
That is a communications finding hiding inside a market report. And it points to a gap in how most companies define IPO readiness.
It is the work of building a company’s public-market storytelling system before the offering window opens. It includes the roadshow presentation, executive on-camera preparation, an investor relations site or microsite, listing day content, and the first-year cadence of earnings and investor communications.
A recovering IPO market does not lower the bar. It raises it. When more companies come to market, investors compare more stories side by side. The offerings that priced well in Q2 shared a pattern: clear positioning inside long-term structural themes, credible leadership, and a narrative investors could understand quickly and repeat accurately.
That last part deserves more attention than it gets. During a roadshow, your story is retold dozens of times without you in the room. Analysts summarize it for portfolio managers. Portfolio managers summarize it for investment committees. Every retelling is a compression test. Stories that were built with discipline survive compression. Stories that were assembled in the final six weeks before pricing usually do not.
Ask most companies what IPO readiness means and you will hear about audited financials, governance structure, internal controls, and legal preparation. All of it is necessary. None of it is sufficient.
Here is what typically happens instead. The financial and legal workstreams get 18 months of runway. The communications workstream gets a sprint. The roadshow deck gets built under deadline pressure by people who are simultaneously drafting an S-1. Executives who have never presented to institutional investors on camera get minimal preparation. The IR website goes live days before it needs to perform. Listing day gets treated as a photo opportunity rather than a produced communications moment with a global audience.
The result is a company with clean financials and an underbuilt story. In a selective market, that gap shows up in the order book.
Sophisticated issuers treat communications as a parallel workstream with its own timeline. Four assets deserve early investment.
The roadshow presentation. This is not a slide deck. It is the master narrative document of the entire offering. Every subsequent communication, from testing-the-waters meetings to the first earnings call, inherits its structure. Companies that invest in narrative architecture and presentation design early give every later asset a foundation. Companies that do not spend the first public year fixing inconsistencies.
Executive on-camera readiness. Public-market investors evaluate leadership constantly, on webcasts, in recorded interviews, and across virtual meetings. An executive who is precise and confident on camera compounds credibility. One who is visibly uncomfortable creates friction that no amount of financial disclosure offsets. Purposeful corporate video production, built around each leader’s natural strengths, closes that gap before it becomes visible to the Street.
Digital infrastructure. Your IR site is where analysts verify what they heard. It needs to carry the same narrative, the same design system, and the same clarity as the roadshow itself. For companies managing complex debuts, dedicated investor relations microsites serve as a controlled source of truth: presentation materials, webcast access, FAQs, and governance messaging in one place.
The listing day moment. Bell ceremonies, broadcast segments, and launch content reach employees, customers, and investors simultaneously. Treating the day as professional live, virtual, and hybrid event production, rather than a ceremonial afterthought, turns a single morning into a durable asset library.
The Q2 data shows both paths to the public markets remain active, with traditional IPOs regaining share as issuer confidence strengthens. From a communications standpoint, the choice of path changes the mechanics, not the requirement. A de-SPAC transaction still demands a clear narrative, prepared executives, and credible investor-facing infrastructure. In some ways it demands more, because SPAC investors can redeem, which makes the story a retention tool, not just a sales tool.
For teams eyeing a 2027 window, a practical sequence looks like this.
Twelve or more months out, build the core narrative and test it against the hardest questions institutional investors will ask. Nine months out, translate that narrative into a designed presentation system and begin executive communications preparation. Six months out, develop the IR digital presence and begin producing the video assets the roadshow and listing day will need. Ninety days out, rehearse. Not once. Repeatedly, on camera, under conditions that resemble the real thing.
None of this requires waiting for bankers to set a timeline. All of it makes the banker-driven sprint dramatically easier when it arrives.
We produce high-stakes investor communications for public and pre-IPO companies, and the pattern we see is consistent. The companies that perform best in front of investors are not the ones with the biggest budgets. They are the ones that treated narrative, design, video, events, and digital as one connected system rather than separate vendor deliverables.
We saw a structurally similar dynamic with Yesway. The company was reintroducing its leadership and reframing its growth story for an investor audience that had not heard from it directly in years. That is, functionally, what a debut is. The content had to work quickly, convincingly, and at the standard a public company’s most critical audience demands. The production system was built to protect that outcome across five executives and three countries.
An IPO compresses the same challenge into a shorter window with higher stakes. Investor audiences do not just evaluate numbers. They evaluate confidence, coherence, and credibility, and production quality either reinforces those signals or works against them.
The market data says the window is reopening and investors are selective. The practical translation is simple. Your financials get you into the conversation. Your story, and how well it is built, told, and produced, determines how the conversation goes.
If a public debut is on your horizon, the best time to pressure-test your communications readiness is before anyone sets a pricing date. If you want a second set of eyes on what that system should look like for your company, we are glad to compare notes.
Ideally 12 months or more before a target window. The narrative and executive preparation workstreams benefit most from runway. Compressed timelines are workable, but they trade polish for speed.
No. Design is the final layer. The roadshow presentation is the master narrative for the offering, and every later communication inherits its structure. Narrative architecture comes first, then visual system, then production.
Yes, and sometimes more. De-SPAC investors can redeem shares, so the story functions as a retention tool. The narrative, executive readiness, and digital infrastructure requirements are equivalent to a traditional debut.
A controlled, consistent source of truth: the company narrative, presentation materials, webcast access, leadership profiles, governance information, and FAQs, all aligned with the roadshow’s messaging and design.
Listing day is a produced broadcast moment reaching investors, employees, and media at once. Companies that plan it as an event production capture content that supports investor communications for months afterward.
Here’s the short version, for boards and IROs who want the takeaway up front: activist preparedness has two layers. The first is governance — the self-assessment and refreshment work Heidrick describes. The second is communications infrastructure — the proxy site, the Investor Day record, the executive video library, and the presentation system that make your value creation story visible, consistent, and verifiable to shareholders before anyone forces the question. Companies that build both layers early control their own story. Companies that build only the first end up arguing from a position of credibility they never made public.
For a broader crisis-readiness framework, see our guide to investor communication strategy. It connects narrative management, executive visibility, digital channels, and rapid-response workflows before pressure arrives.
In June, Heidrick & Struggles published a board effectiveness insight built on Benjamin Franklin’s old line about an ounce of prevention. Their argument: shareholder activism has become too frequent, too sophisticated, and too board-focused to treat as a crisis you respond to. It’s a condition you prepare for.
The numbers behind that argument are hard to ignore. Heidrick reports that activists launched a record 255 campaigns globally in 2025, with the US accounting for 141. That’s a 23% year-over-year increase. Nearly a third of campaigners were first-timers, and more than a third of all campaigns explicitly targeted board change: refreshment, governance reform, leadership credibility. The contest is no longer just about strategy. It’s about the people overseeing it.
The cost of getting caught flat is equally concrete. Citing Deal Point Data, Skadden reported that the eight US proxy contests that went to a vote in the first half of 2025 cost target companies $69.1 million in aggregate, roughly $8.6 million per company, before you count management distraction, delayed execution, and the internal erosion that follows a public fight.
Heidrick’s prescription is a four-part preventive discipline: stress-test your own vulnerabilities the way an activist would, run a forward-looking diagnostic of board composition and performance, insist on decision-grade data rather than reassuring dashboards, and build a credible value creation narrative.
It’s a strong framework. We’d push on one point: the fourth step is where most companies stop one move short. Because a narrative that exists only in the boardroom isn’t a defense. It’s a draft.
One of the sharpest observations in the Heidrick piece is that activists rarely win by uncovering something new. They win by taking familiar, public facts from filings, TSR comparisons, segment economics, board tenure and assembling them into a story that’s more pointed than the company’s own.
Read that from a communications perspective and the implication is uncomfortable: an activist campaign is, at its core, a competing content operation. The activist arrives with a thesis, a deck, a website, and a media plan. If the company’s answer is a hastily assembled press release and a proxy statement written for compliance rather than persuasion, the activist doesn’t need better facts. They just need a better-built argument.
This is also why one of the blind spots Heidrick flags is inconsistent messaging across earnings calls, proxies, and investor decks and matters more than it looks. Inconsistency isn’t just sloppy. It’s raw material. Every gap between what the CEO said in March and what the deck showed in September is a slide in someone else’s presentation.
In our experience producing contested-situation and investor communications, the pattern is consistent. Companies don’t lose the narrative fight because they lack a story. They lose it because they try to build the delivery system for that story in the middle of the fight.
That looks like: standing up a shareholder site in days under legal review pressure. Recording executive video for the first time when the executives are already defensive. Rebuilding the investor deck mid-contest because the standing version was written for a friendlier audience. Discovering that the company’s last visible, produced statement of its own strategy is three years old.
None of this is a strategy failure. It’s an infrastructure failure. And it’s preventable in exactly the sense Franklin meant.
So what does activist-ready communications actually look like? Four assets, built or maintained before you need them.
A digital center of gravity. In a contested situation, shareholders, proxy advisors, and journalists all ask the same question: where is the company’s case? A proxy fight site answers it in one controlled destination for the board’s recommendation, materials, governance messaging, video, FAQs, and voting information.
When we built the proxy defense site for Victoria’s Secret & Co., We built the site alongside executive video interviews across three locations because stakeholders based the contested vote on both the supporting documents and whether leadership looked and sounded like a team worth backing. Companies that map their information architecture, messaging, and approval processes before a contest begins are best positioned to launch a site like this quickly.
A public record of the value creation story. Heidrick argues that the strongest narratives have coherence, credibility, and continuity. Investor Days are where all three get tested in public. The board’s answer to “why this strategy, why this team, why now,” delivered on the record is why Investor Day production belongs in an activist-preparedness conversation, not just a marketing calendar. It’s also why the connection runs both directions: often times we’ll create a proxy fight site and the produce a full Investor Day shortly thereafter, turning a complex multi-business story into one coherent investor experience. The site holds the line; the event proves the case.
An executive presence that already exists. The first time investors see your CEO on camera should not be during a contest. Year-round investor relations content such as strategy explainers, leadership interviews, segment stories builds the familiarity and credibility that a defense campaign can draw on instead of manufacture.
A presentation system, not a deck. The proxy, the earnings deck, the Investor Day materials, and the contested-situation presentation should read as chapters of one book. Heidrick notes that leading boards now treat the proxy as a strategic narrative rather than a compliance document. We’d extend that to every investor-facing asset: same story, same structure, same visual logic. Consistency is the cheapest credibility you can buy.
Investor audiences don’t only evaluate the numbers. They evaluate confidence, coherence, and control — and they read those qualities partly through the quality of what a company puts in front of them. A defense that arrives late, looks improvised, or contradicts itself does damage no set of facts can fully repair.
That’s why we think of activist preparedness the way Heidrick thinks of board effectiveness: as ongoing discipline, not episodic response. The board does the governance work. Someone has to build the system that carries it — and the time to build it is when nothing is on fire.
If a campaign never comes, none of this is wasted. A strong proxy-ready microsite becomes an IR content hub. Investor Day materials compound into a public strategy record. Executive video keeps working across recruiting, media, and shareholder engagement. Prevention, done well, is just good investor communications with a harder edge.
If your board is doing the self-assessment work Heidrick recommends, it’s worth asking one more question in the same session: if the letter arrived Monday, what would shareholders find when they went looking for our side of the story? If the honest answer is “not much yet,” that’s the gap to close — and we’re glad to talk through what closing it looks like.
A proxy fight website is a dedicated digital destination used during a contested shareholder situation to present the company’s position, board recommendations, key materials, voting information, and supporting content in one controlled place. It may also be called a proxy contest website, activist defense website, or shareholder communications site.
Ideally before it needs one. Mapping the information architecture, messaging, and approval process in advance means a site can launch in days rather than weeks when a situation turns contested — and the same foundation can serve as an IR content hub in the meantime.
An Investor Day puts the board’s value creation narrative on the public record — strategy, leadership, capital allocation, and targets, delivered in the company’s own voice. That record makes it materially harder for an outside party to reframe familiar facts into a competing story.
According to Skadden, citing Deal Point Data, the eight US proxy contests that went to a vote in the first half of 2025 cost target companies $69.1 million in aggregate — about $8.6 million per company — before accounting for management distraction and reputational drag.
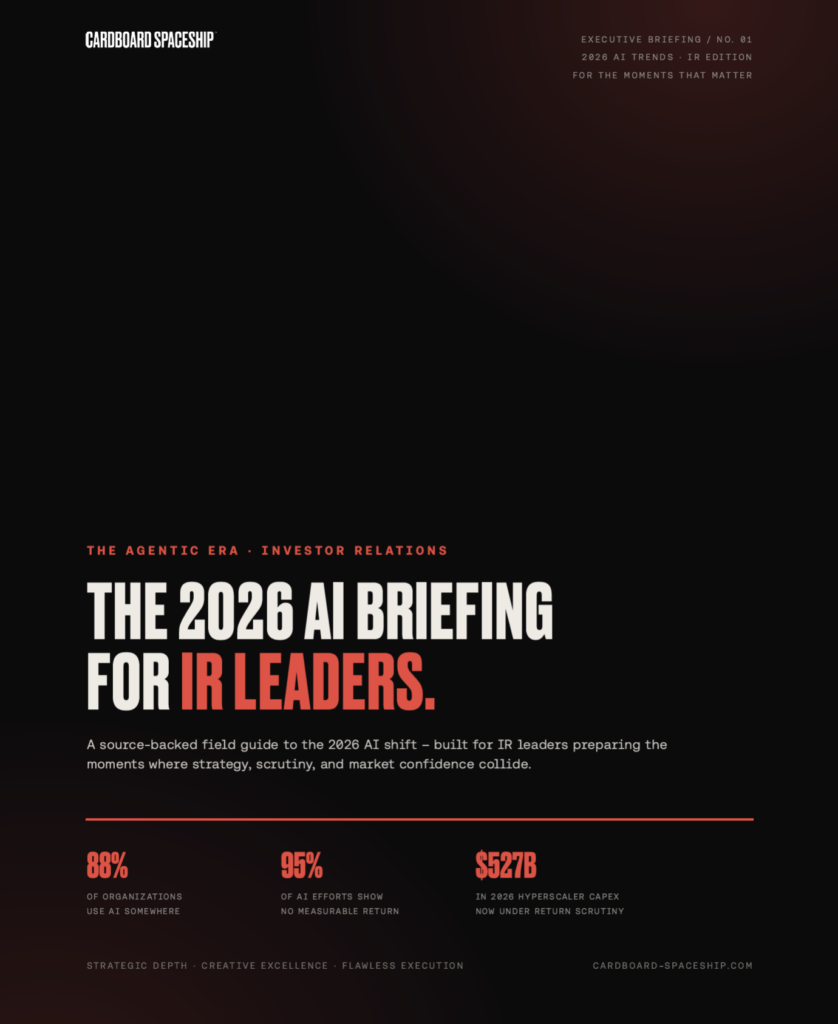
AI moved from innovation language into investor language faster than most companies built the operating model to back it up. Today 88% of organizations use AI somewhere – yet roughly 95% of AI efforts show no measurable return, and investors have stopped rewarding AI spend on faith. With 2026 hyperscaler capex tracking toward $527B, the market is openly pricing the gap between what companies claim about AI and what they can prove.
That gap is now an IR problem. AI claims don’t stay inside product and engineering teams – they surface on earnings calls, in Investor Day narratives, in launch demos and roadshow conversations – and a credibility gap quietly becomes an equity-story gap. Mastering AI for investor relations means making your company’s AI story specific, financially grounded, and staged so a skeptical room can believe it.
The 2026 AI Briefing for IR Leaders is a source-backed field guide to that work. Inside, you’ll get the five shifts redefining the AI conversation, a framework for connecting AI spend to return, the five Demo Modes for staging proof without ceding the narrative, eight practical moves to make now, and a one-page pre-event readiness checklist you can run before the room fills.
In May 2026, the SEC proposed optional semiannual reporting: the option for public companies to report twice a year instead of four times. Under the proposal, a company could file a single semiannual report on a new Form 10-S in place of three quarterly 10-Qs, keeping only the year-end annual report on top of it. The comment period runs through early July, and if the rule is adopted, some calendar-year companies could be making the election as early as their next annual filing.
It is easy to read that as a story about paperwork, but it is not. The SEC’s proposed semiannual reporting option changes how often companies are required to file – but it does nothing to change how closely the market watches. Analysts will still build their models. Institutional holders will still look for signals. Boards, employees, and the financial press will still expect a clear read on where the business is heading. The disclosure floor may drop. The demand for understanding does not move at all.
Strictly speaking, filing less and communicating less are two separate decisions (the regulation governs the first, not the second). But for most companies they will not stay separate on their own.When you remove a deadline, voluntary output tends to drift down, not hold steady. Report less, and you’ll communicate less – unless IR teams deliberately rebuild the rhythm the quarterly filing used to enforce.
So the meaningful question for investor relations teams is not “Can we stop reporting every quarter?” It is “How do we keep confidence high when the formal reporting cadence slows down?”
Short answer
Semiannual reporting changes filing frequency, not the market’s need for information – and the SEC’s proposal leaves earnings calls and releases untouched. Companies that simply report less create an information vacuum that others will fill. The stronger move is to replace the quarterly disclosure rhythm with a deliberate engagement system: investor letters, KPI explainers, executive video, conference content, and an always-on investor hub that becomes the source of truth between filings.
The mechanics matter, because they shape the decision. The proposal is optional. Companies that prefer the current cadence keep filing three 10-Qs and one 10-K. Those that elect the new path file one Form 10-S covering the first half of the year, plus their annual report. The SEC has framed this as flexibility – letting companies and their investors choose the interim frequency that fits the business rather than applying a single rule written for a very different market decades ago.
Two details are easy to miss and important for IR planning.
In other words, the regulation sets a lower minimum, but it does not require silence. What a company does with the space between filings becomes a strategic decision, not a compliance default.
For most public companies, the quarterly report was never only a disclosure obligation. It was a forcing function. A recurring, scheduled reason for leadership to explain progress, reset expectations, name risks before someone else did, and connect the latest numbers back to the long-term strategy. Remove three of those four moments and you do not just remove filings. You remove the cadence that kept the company’s story in front of the market on a predictable schedule.
That cadence does not have to disappear. But it will not maintain itself.
Left alone, a thinner calendar tends to produce longer silences, and silence in capital markets is rarely neutral. Analysts fill gaps with assumptions. Investors price in uncertainty. The story drifts toward whatever interpretation is loudest, which is frequently not the company’s own.
The first mistake is treating the choice as a finance or legal decision alone.
Whether to elect semiannual reporting is, in large part, a communications decision. About how a company wants to be understood, how much friction it is willing to introduce for the analysts who cover it, and whether comparability with quarterly-reporting peers will help or hurt its valuation.
The second mistake is assuming “report less” and “communicate less” are the same thing. They are not. The companies most likely to struggle with a thinner calendar are the ones that quietly let engagement lapse and hope the next report does the heavy lifting. By then, perception has already set.
The disciplined approach is to design an engagement system before changing the cadence, so the new rhythm is intentional rather than accidental. In practice, that system tends to include a handful of connected pieces:
The format matters less than the discipline behind it: consistent messaging, steady proof points, and a clear path from performance to strategy that holds together across the year.
Here is the principle underneath all of this: a strong investor narrative is not decoration. It is infrastructure for understanding. When the regulatory scaffolding that used to organize the year comes down, the company has to supply its own structure. And that structure is built out of communication, not compliance.
It also helps to stop thinking about these assets as separate line items. The investor letter, the executive video, the conference deck, the investor microsite that serves as a single source of truth – these are not a checklist. They are connected parts of a singular investor experience, and they either reinforce each other or they create friction. A polished video paired with a confusing data page does not read as “polished video, confusing page.” It reads as a company that does not understand its own story.
Fewer filings also raise the value of the moments that remain. A semiannual cadence makes set-piece events – the Investor Day, the roadshow, the strategy update – carry more weight, because there are fewer of them to carry the year. The companies that treat those moments as orchestrated communications events, not just meetings with slides, will get more out of each one. That is where executive video, CEO messaging, and disciplined presentation design move from “nice production” to true signal: in capital markets, production quality either reinforces confidence or introduces doubt, and there is rarely a neutral option.
Concretely, for a company that elects semiannual reporting, that system has a shape. The half-year report anchors the calendar, but it no longer stands alone.
That is the difference between reporting less and going quiet – and it is work that must be designed, not improvised.
If your company is weighing the semiannual election – or simply watching the proposal move through its comment period – the most useful thing you can do now is separate two questions that often get merged. One is a filing question: does a lighter calendar fit our business, our peers, and our investor base? The other is a communications question: if we file less, what is our deliberate plan to keep the market informed, confident, and aligned with our strategy in between?
A lighter filing calendar does not have to mean a quieter company. Handled well, it can create room for sharper storytelling, better-designed updates, and a more intentional investor experience — one built on the company’s own terms rather than the disclosure calendar’s.
If you’re weighing the semiannual election, the engagement plan belongs in the decision, not after it. That’s the work Cardboard Spaceship does – building the narrative, video, presentation, and microsite moments that keep the market confident in the quarters without a formal filing.
=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>=””>-attribute-key=”content”>No. The SEC proposed making semiannual reporting optional. Companies could elect to file a single semiannual report (Form 10-S) plus their annual report, or keep the current schedule of three quarterly reports and one annual report. As of mid-2026 it is a proposal, with the public comment period closing in early July 2026.
Not necessarily. The proposal changes the minimum filing requirement, not communication strategy. It does not alter the frequency of earnings calls or releases, and electing companies could still publish first- and third-quarter financials voluntarily. How much a company communicates between filings becomes a choice.
The main risks are perception-related: longer gaps can create information vacuums that analysts and investors fill with their own assumptions, and reporting on a different cadence than quarterly-filing peers can introduce comparability challenges. Strong, consistent between-filings engagement is what offsets those risks.
A clear narrative connecting performance to strategy, KPI explainers, executive video, conference and roadshow content, targeted shareholder outreach, and an always-on investor hub that consolidates the story and the data in one place.
Treat it as two questions, not one. First, the filing question: does the lighter calendar suit your business model, investor base, and peer set? Second, the communications question: do you have a deliberate plan to keep the market confident in the quarters without a formal report? The second question is where most of the real risk – and opportunity – lives.
The afternoon before Satya Nadella walked onto a stage at Fort Mason, Microsoft Copilot went dark. More than 2,600 enterprise users reported outages on Downdetector before noon on June 1, 2026. The failure locked people out of workflows their companies had rebuilt around the assistant. Twenty-four hours later, Nadella opened Microsoft Build 2026 by promising autonomous agents that would run those workflows on their own.
That gap – between the failure and the promise – is where this story starts. But it is not what the story is about. For three years, the question facing every public company with an AI story was simple: do you have it? Build 2026 is where that question quietly died. Nobody in the room doubted Microsoft has AI.
The sharper shift wasn’t the question. It was who is now asking it.
The first reader of your earnings call is increasingly not a person but a machine. It is an AI agent that summarizes and scores you for the analyst before a human looks. At Build, Microsoft spent two days building exactly that kind of system. This piece is about the audience it creates: what we call the agentic audience. And what every team working in investor relations in the agentic era must do to earn an accurate read.
Here is the uncomfortable part. An investor moment built only for the people attending (live or virtually) is now half-built. The other half of your audience never shows up, never applauds, never forgets. And it is already grading you. The investor moment used to be a pitch. It is becoming an audit, one you volunteer for the moment you publish.

The agentic audience is the growing layer of AI systems that read, summarize, and score a company’s communications before any human does. It is the model an analyst runs across your earnings transcript to extract guidance. The tool that sentiment-scores management’s tone on the call. The agent that reconciles your slide deck against your filings and flags what does not match. By the time a human analyst forms a view, a machine has often already shaped it.
Build 2026 turned that abstraction into something you can point at, because Microsoft spent the keynote building the very class of system that does this work. It unveiled seven in-house MAI models, among them the reasoning model MAI-Thinking-1 and MAI-Transcribe-1.5, which handles 43 languages. They are summarizers, sentiment-scorers, and reasoning engines. In other words, they are the exact tools that now sit between a company and its investors. The company that demonstrated the agentic audience most vividly is also one of the companies building it. Microsoft did not invent this reader, and it is not building it alone. Google, OpenAI, and Anthropic are racing on the same class of system. What Build offered was the clearest view of it: the whole stack on one stage, in public – models, agents, web-grounding, governance.
Web IQ is the Bing-built service Microsoft unveiled to pull live web information into AI answers. And it already feeds both Microsoft Copilot and ChatGPT. Read that twice. The machine forming a view of your company is, increasingly, a handful of systems owned by the same companies whose clouds you publish on, whose models you depend on, and whose platforms you compete with. The agentic audience is not a neutral crowd assembling on its own. Someone is building it, and the supplier list is short.
Nothing announced at Build governs how an outside model reads or summarizes you. Microsoft’s governance story was real but pointed elsewhere: Agent 365 controls what your agents can touch and spend. The party being summarized has no equivalent protection. The reader is consolidating, and no one is accountable for the read.

A machine does not read the way a room does, and that single fact rewrites the job.
It cannot be charmed. Not by a confident founder, not by a clean slide, not by the conviction that carries a room. It does not attend a presentation; it parses one. It extracts the claims, checks them against the rest of your disclosures, and scores what reconciles. Charisma was always part of the IR toolkit. The agentic audience is immune to it. What it rewards instead is verifiability – a claim it can reconstruct, not one it has to trust.
This is why “do you have AI?” gave way to a harder set of questions. Can you govern it, can you reproduce the results you claim, and can you earn back what you spend. Each one is a question a machine can actually check.
Microsoft built its keynote to answer them in evidence rather than adjectives. It owned its reasoning model outright, trained without distillation. It unveiled an agent platform whose first Autopilot, Scout, runs on the open-source OpenClaw wrapped in enterprise governance. And Microsoft Foundry, a consumption-billing model, turned agent work into metered, countable usage.
Capability was the last decade’s contest. The next one is quieter and harder to fake: it rewards the company that AI can verify. A version of it has already played out in publishing. There, AI summaries answer for the source before readers ever click through. The businesses on the other end feel it, in their traffic and their revenue.
You cannot charm this reader. You can only hand it something to confirm. Numbers that reconcile across every document. Claims it can check on its own. Proof it can rebuild without taking your word for any of it. That is what reading you well now requires. The reader is here, and it is forming a view. The only question left is whether you have given it a story true enough to support.
You could watch this happen in real time at Build. Microsoft shares had run well off their late-March low going into the week, but the stock slipped during the event itself, sliding roughly 3 to 4% across June 2 and 3 to around $430.80. The pattern of that sell-off is the agentic audience caught in the act.
The market discounted the spectacle – a next-generation Majorana 2 quantum chip it could not yet price – and bore down on the one figure it could verify and model: performance per watt, where Microsoft claimed a 1.4x gain from running its own MAI models on its own Maia 200 chips. It rewarded what reconciled and marked down what it could not check. That is not how a crowd responds to a great show. It is how a system reads. The agentic audience was no forecast at Build; it was already in the tape, grading the most consequential AI company on earth in real time.
The bull case ran on the same currency. Morgan Stanley’s Keith Weiss argued Wall Street is underestimating the revenue Microsoft’s AI data-center spending will generate – by as much as 91% – and set a $650 price target against a roughly $557 “Strong Buy” consensus. Wedbush’s Daniel Ives, calling the recent OpenAI restructure a net positive, raised his to $575 and noted Microsoft will now collect roughly $6 billion from OpenAI in 2026. Notice what those targets rest on: not vision, but modeled, reconcilable numbers – revenue per megawatt, dollars per token, performance per watt. Even the human analysts are reading like the machines now.

None of this retires production. An investor moment is still a human performance. You are still building conviction, sequencing a story, earning a room’s trust in the span of a morning. The agentic audience does not replace that work. It adds a second, colder reading on top of it. A machine that was never in the room now parses everything you build for the people in it. The discipline is producing one event that lands both ways.
The two audiences reward different things, which is harder than it sounds. A few of the considerations that change how we build:
The agentic audience reads the transcript, the deck, and the filing. It does not read the lighting, the pause before the big number, or the certainty in a CEO’s voice. A point that landed only on its delivery will not survive the compression into text. The meaning has to live in the record, not only in the performance.
The agentic audience scores reconciliation a human eye forgives. Every figure has to tie across every document a system cross-references – deck, press release, 10-Q, transcript, call. The mismatch a person skims past is the exact thing the model flags. Consistency also runs across time. The reader holds your last several quarters and compares them in seconds. A quietly reclassified segment or redefined metric reads as drift. Flag the change before the model catches it.
It can’t hear conviction, but it reads the words that carry it. Hedging, heavy qualifiers, and a defensive Q&A answer register as uncertainty. One shaky line can color an otherwise strong quarter. Confident language is not only better for the room. It also scores better on the page.
A machine cannot infer the setup. The claims you most want understood have to be the easiest ones to extract and still be true. Say a number needs three slides of context to mean what you intend. The summary will keep the number and drop the context.
A machine can rebuild proof, so proof is what it rewards. Microsoft modeled this on stage. Its strongest demonstrations were the ones the audience could go run that same afternoon. The new coding model reached developers the day it launched, and the models rolled out live rather than “coming soon.” Our five Demo Modes for reading live AI demonstrations need a sixth: Verified Reproducible. Its credibility comes not from how it looked, but from how easily the audience can rebuild it. The IR translation is exact. An analyst – or the analyst’s AI – can rebuild a number from your filings. That number beats the one you ask anyone to take on faith.
Production craft is not exempt from this. If anything, it matters more. This year, Microsoft shrank Build into the workshop-scaled Fort Mason Center. It was a smaller, more exposed room than the stadium productions of years past. The choice traded spectacle for intimacy to rebuild developer trust. A smaller room is harder to produce, not easier – there is nowhere for thin material to hide. But the same instinct serves the AI analyst. A room built on substance rather than spectacle produces a clean record: proof-dense, claim-forward, easy to reconstruct. The production decisions that earn a skeptical room’s trust are, increasingly, the same ones that survive an agentic read.
A few overlooked materials become the load-bearing part of an investor moment. Each decides whether the story you told the room is the one that travels beyond it:
The last move is the one most teams skip.
After the event, query the major models and agents the way a covering analyst would. Read how they summarize you. Say they miss the thesis, mangle the guidance, or quote a number out of context. That is not a model problem. It maps exactly where your materials fell short, and you now know what to fix before the next one. The agentic read is no longer something to anticipate. It is something you can test, the same way you would rehearse a run-of-show. That is the difference between a team that talks about the agentic audience and one that produces for it.
None of these are particularly glamorous. They are what decides whether the story you told the room is the story that sticks.
This is what we consider when we approach any investor moment, live event, or public production. The room still gets the cinematic, human experience it came for: the narrative arc, the presence, the conviction that moves people. But we make sure that every asset that leaves the building will survive the second, thorough machine reading.
It echoes something we explored in Coinbase’s recent work: proving real human craft in a synthetic age. Build 2026 is the other side of the same coin. Coinbase had to prove provenance: that real people made the work. The agentic era asks for accountability: that the claim holds up to scrutiny. Both answer the one question that now defines high-stakes communication. When everyone assumes capability, and software can fake or automate almost anything, how do you generate trust?
The companies that own the agentic era will take the new reader seriously now. They will decide how the world understands them before a model decides for them. The ones that wait will not get a warning. They will simply find their story reaching the analyst pre-summarized. A model they never met will have framed it, in words they did not choose.
Your next investor isn’t only human. The audience now includes a machine that reads first, forgets nothing, and cannot be won over. At Build 2026, Microsoft showed everyone what it looks like by building it. You do not win that room with a better show. You win it with a story built from planning to playback. Both the people deciding and the machine briefing them have to read it the same way. That is the work, and it is worth starting before the reader starts deciding for you.
Microsoft Build 2026 centered on agentic AI. The headline announcements included seven in-house MAI models (led by the reasoning model MAI-Thinking-1), a new category of autonomous agents called Autopilots – the first, Scout, runs on the open-source framework OpenClaw – the Maia 200 AI chip, the Project Solara agent platform, and the Majorana 2 quantum chip.
Build 2026 marked the moment the investor question shifted from “do you have AI?” to whether a company can govern, reproduce, and monetize it. For IR teams, it signals that capability is now assumed and proof – of control and return – is the new mandate.
The Agentic Audience is the idea that the first reader of your earnings transcript, investor day deck, or keynote is increasingly an AI system that summarizes and sentiment-scores you for the analyst before a human reads a word. Companies now produce investor communication for both humans and the models that brief them.
Microsoft stock fell roughly 3–4% across June 2–3, 2026, to around $430.80. Investors treated the flashiest reveal, the Majorana 2 quantum chip, as a long-term catalyst, and kept pressing on AI capital spending, margins, an expanded FTC probe, and broader macro headwinds.
Beyond its core AI platform, Microsoft Build 2026 introduced Azure HorizonDB, a managed PostgreSQL service for agentic apps; a GPU-accelerated Fabric Data Warehouse for faster analytics; Project Rayfin, a managed backend-as-a-service on Microsoft Fabric that closes the prototype-to-production gap; the MAI-Voice-2 and MAI-Transcribe-1.5 models, the latter covering 43 languages; and Web IQ, a model-agnostic, MCP-native grounding layer that already powers both Microsoft Copilot and ChatGPT.
The agentic era is rewriting what proof looks like in front of investors, and the companies that adapt first will set the standard. If you are planning a high-stakes moment and want to build it to convince both the room and the models reading it, let’s start a conversation.